Mastering the 50/30/20 Budget Rule for US Households in 2026
Anúncios
The 50/30/20 budget rule allocates 50% of income to needs, 30% to wants, and 20% to savings and debt repayment, offering a straightforward framework for US households to achieve financial stability.
Anúncios
Are you ready to take control of your finances in 2026? Mastering the 50/30/20 budget rule for US households in 2026: A practical solution guide offers a straightforward yet powerful framework to simplify your financial life, making budgeting accessible and effective for everyone.
Anúncios
Understanding the 50/30/20 Budget Rule’s Core Principles
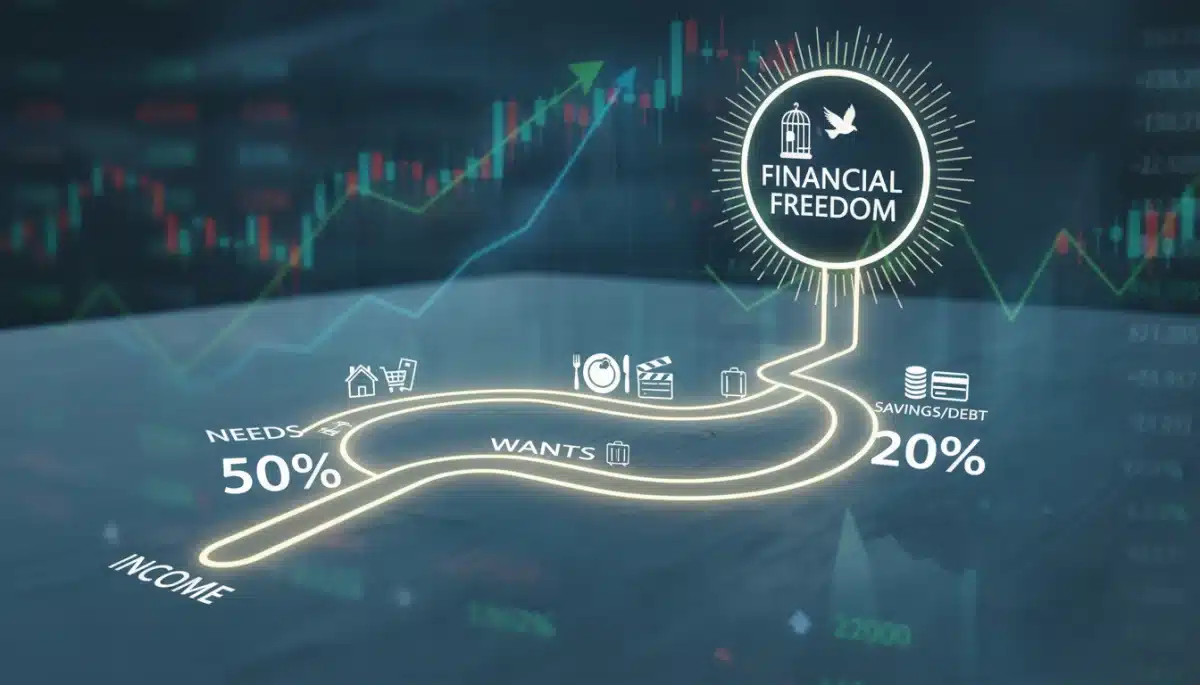
The 50/30/20 budget rule is a popular personal finance guideline that helps individuals and families manage their money effectively. It proposes dividing after-tax income into three main categories: 50% for needs, 30% for wants, and 20% for savings and debt repayment. This simple structure provides a clear roadmap for financial health without being overly restrictive, allowing flexibility while encouraging responsible spending and saving habits.
Originating from Senator Elizabeth Warren and her daughter Amelia Warren Tyagi’s book, ‘All Your Worth: The Ultimate Lifetime Money Plan,’ this rule has gained widespread acceptance due to its ease of understanding and application. For US households navigating the economic landscape of 2026, adapting this rule can be a cornerstone for achieving financial goals, whether it’s saving for a down payment, paying off student loans, or building an emergency fund.
The Three Pillars: Needs, Wants, and Savings/Debt
Breaking down your expenses into these three categories is the first crucial step. Understanding what truly falls into each bucket is vital for accurate budgeting and effective financial management. This distinction can sometimes be blurry, but with a clear definition, you can make informed decisions about your spending.
- Needs (50%): These are essential expenses required for survival and maintaining your current lifestyle. They include housing (rent or mortgage), utilities, groceries, transportation, insurance, and minimum loan payments. Without these, your basic well-being would be compromised.
- Wants (30%): These are discretionary expenses that improve your quality of life but are not strictly necessary. Examples include dining out, entertainment, vacations, subscriptions, new gadgets, and designer clothes. While enjoyable, these can be reduced or eliminated if finances become tight.
- Savings & Debt Repayment (20%): This category is dedicated to building your financial future and reducing liabilities. It includes contributions to an emergency fund, retirement accounts (401k, IRA), investment accounts, and any extra payments towards high-interest debts like credit cards or student loans beyond the minimum.
By clearly defining and categorizing your expenses, you gain valuable insights into where your money is going. This clarity empowers you to make conscious choices, ensuring that your spending aligns with your financial priorities and long-term objectives. The beauty of the 50/30/20 rule lies in its simplicity, making it a powerful tool for financial empowerment.
Calculating Your After-Tax Income in 2026
Before you can apply the 50/30/20 budget rule, you need to accurately determine your after-tax income. This is the amount of money you actually take home after all deductions, such as federal, state, and local taxes, as well as contributions to health insurance, retirement plans, and other pre-tax benefits. In 2026, with potential shifts in tax codes and benefit structures, precise calculation is more important than ever.
Your gross income is your total earnings before any deductions. From this, various amounts are withheld. These withholdings can vary significantly based on your employment status, state of residence, and the elections you make during your employment onboarding. Understanding these deductions is key to knowing your true disposable income.
Key Deductions to Consider
Several standard deductions impact your take-home pay. While some are mandatory, others are elective and can be adjusted to better suit your financial goals. Being aware of these helps you accurately calculate the base for your budgeting.
- Federal, State, and Local Taxes: These are non-negotiable and typically represent the largest portion of your deductions. Tax rates can change, so it’s wise to review your withholdings annually or when there are significant life changes.
- Health Insurance Premiums: If your employer provides health insurance, your share of the premiums is usually deducted from your paycheck before taxes. This is a crucial ‘need’ expense that often reduces your gross income.
- Retirement Contributions (e.g., 401(k), 403(b)): While these are technically savings, many are pre-tax contributions, meaning they reduce your taxable income. For the purpose of the 50/30/20 rule, it’s often easiest to calculate your budget based on your net pay after these pre-tax deductions have been made, then count any additional retirement savings as part of your 20% savings category.
- Other Pre-Tax Benefits: This could include contributions to Health Savings Accounts (HSAs), Flexible Spending Accounts (FSAs), or commuter benefits. These also reduce your taxable income and should be factored in before determining your after-tax income for budgeting.
To get your precise after-tax income, review your pay stubs or use an online paycheck calculator. Many financial institutions and government websites offer tools to help you estimate your net pay. Once you have this accurate figure, you can confidently allocate your funds according to the 50/30/20 rule, ensuring your budget is built on a solid foundation.
Allocating Your Income: Needs (50%)
The 50% allocation for needs is the bedrock of the 50/30/20 budget rule. These are the non-negotiable expenses that keep a roof over your head, food on your table, and ensure your basic well-being. Accurately identifying and prioritizing these costs is essential for financial stability, especially for US households navigating the economic realities of 2026.
It’s easy to underestimate or miscategorize expenses as ‘needs’ when they might actually be ‘wants.’ A critical self-assessment is required here. For instance, while housing is a need, a lavish apartment or a large house beyond your means might push your housing costs beyond the 50% threshold, indicating a need for adjustment.
Common Needs for US Households
Here’s a breakdown of typical expenditures that fall into the ‘needs’ category. Evaluating these against your actual spending will help you align with the 50% guideline.
- Housing: This includes rent or mortgage payments, property taxes, and homeowner’s insurance. These are often the largest single expense for many households.
- Utilities: Electricity, gas, water, internet, and essential phone services are vital for daily living.
- Groceries: Food is a fundamental need, but this category should focus on essential foodstuffs rather than gourmet items or excessive dining out.
- Transportation: Car payments, fuel, public transport fares, car insurance, and necessary maintenance fall here. If you rely on a vehicle for work or daily life, these are essential.
- Healthcare: Health insurance premiums (if not pre-tax), co-pays, prescription medications, and necessary medical supplies.
- Minimum Loan Payments: This includes the minimum payments on student loans, car loans, and credit card debt. While the goal is to pay more, the minimum is a need to avoid penalties.
If your needs exceed 50% of your after-tax income, it’s a clear signal that you need to re-evaluate your core expenses. This might involve looking for more affordable housing, reducing transportation costs, or finding ways to cut down on utility bills. Adjusting your needs can be challenging, but it’s a vital step towards achieving a balanced budget and freeing up funds for savings and wants.
Strategic Spending: Wants (30%)
The ‘wants’ category, accounting for 30% of your after-tax income, is where you have the most flexibility and control. These are the expenses that enhance your lifestyle and provide enjoyment, but are not strictly necessary for survival. For US households in 2026, understanding how to strategically manage this portion of your budget is key to both financial health and personal satisfaction.
Distinguishing between needs and wants can sometimes be tricky. For example, while food is a need, dining out at expensive restaurants multiple times a week is a want. Similarly, a basic phone plan is a need, but the latest smartphone model or premium streaming services are wants. Consciously identifying these differences empowers you to make deliberate spending choices.
Managing Your Discretionary Spending
This 30% allows for personal enjoyment and leisure, but it also requires discipline. Without careful management, ‘wants’ can easily creep into the ‘needs’ category, disrupting your entire budget. Here are some common wants and strategies to manage them:
- Entertainment: Movies, concerts, sporting events, video games, and hobbies. Consider free or low-cost alternatives, or set a monthly entertainment budget.
- Dining Out & Takeaway: Eating at restaurants, ordering delivery, or frequent coffee shop visits. Cooking at home more often can significantly reduce these costs.
- Travel & Vacations: While enriching, these are discretionary. Plan ahead, seek deals, or opt for staycations to manage expenses.
- Shopping (Non-essentials): New clothes (beyond basic necessities), accessories, electronics, and home decor items. Practice mindful consumption and differentiate between impulse buys and genuinely desired items.
- Subscription Services: Multiple streaming platforms, gym memberships (if not actively used), and various apps. Regularly review and cancel unused subscriptions.
The goal isn’t to eliminate all wants, but to ensure they fit within your allocated 30%. This portion of the budget is about intentional spending that brings you joy without jeopardizing your financial stability. By being mindful of your wants, you can enjoy life’s pleasures responsibly while still making progress towards your financial goals.
Building Wealth: Savings & Debt Repayment (20%)
The 20% allocated to savings and debt repayment is arguably the most critical component of the 50/30/20 budget rule for long-term financial health. This portion of your income is dedicated to building your financial future, creating a safety net, and reducing liabilities. For US households in 2026, consistent application of this rule can lead to significant wealth accumulation and debt freedom.
This category is about investing in yourself and your future. It’s not just about putting money aside; it’s about strategically allocating funds to maximize returns and minimize financial burdens. Prioritizing this 20% ensures that you are always working towards financial independence, no matter what economic challenges arise.
Key Areas for Your 20% Allocation
Where you direct this 20% depends on your current financial situation and goals. It’s often a combination of different vehicles, each serving a specific purpose in your financial plan.
- Emergency Fund: This should be your top priority if you don’t have one. Aim for 3-6 months’ worth of essential living expenses in an easily accessible savings account. This fund protects you from unexpected job loss, medical emergencies, or unforeseen home repairs.
- High-Interest Debt Repayment: After establishing an emergency fund, aggressively tackle high-interest debts like credit card balances. The interest saved can be substantial and accelerate your path to financial freedom.
- Retirement Savings: Contribute to your 401(k), IRA, or other retirement accounts. If your employer offers a match, contribute at least enough to get the full match – it’s free money!
- Investment Accounts: Once your emergency fund is robust and high-interest debt is managed, consider opening a brokerage account to invest in stocks, bonds, or mutual funds for long-term growth.
- Specific Savings Goals: This could include saving for a down payment on a house, a child’s education, a new car, or any other significant future expense.
Consistently dedicating 20% of your income to these areas transforms your financial trajectory. It moves you from merely surviving to thriving, building a secure future where you have more options and less stress. This commitment to saving and debt repayment is an investment that pays dividends for years to come.
Adapting the Rule for US Households in 2026
While the 50/30/20 budget rule provides an excellent framework, its rigid percentages might need adaptation for the diverse financial realities of US households in 2026. Economic conditions, regional cost of living, and individual circumstances can all influence how feasible a strict 50/30/20 split is. The key is to use the rule as a guide, not a strict mandate, adjusting it to fit your unique situation.
For instance, in high cost-of-living areas, housing and essential utilities might naturally consume more than 50% of an income. Conversely, individuals with lower essential expenses might find they can allocate more to savings or wants. The flexibility of the rule lies in its principles, which can be applied even if the percentages shift slightly.
Flexibility and Personalization
Don’t be discouraged if your initial budget doesn’t perfectly align with the 50/30/20 split. The goal is progress, not perfection. Here are ways to personalize the rule:
- The 60/20/20 or 40/30/30 Approach: If your needs are exceptionally high, you might start with a 60/20/20 split (60% needs, 20% wants, 20% savings). If you have significant debt or aggressive savings goals, a 40/30/30 (40% needs, 30% wants, 30% savings) might be more suitable.
- Temporary Adjustments: Life happens. A sudden medical expense or a period of unemployment might temporarily shift your percentages. The important thing is to return to your target allocations as soon as circumstances allow.
- Income Fluctuations: For those with variable incomes, base your budget on your lowest expected income, or average your income over several months. Then, allocate any extra income during high-earning periods towards savings or debt repayment.
- Review and Revise Regularly: Your financial situation isn’t static. Review your budget quarterly or semi-annually. Adjust allocations as your income changes, expenses shift, or financial goals evolve.
The power of the 50/30/20 rule is its ability to foster financial awareness and discipline. By understanding your spending patterns and making conscious choices, you can adapt this powerful tool to serve your specific needs, ensuring long-term financial success and peace of mind in the ever-changing economic landscape of 2026.
Tools and Resources for Budgeting Success
Implementing the 50/30/20 budget rule effectively requires more than just understanding the percentages; it demands practical tools and consistent tracking. Fortunately, in 2026, US households have access to a wealth of digital and traditional resources that can simplify the budgeting process, making it easier to monitor spending and stay on track with financial goals.
Choosing the right tools can make a significant difference in your budgeting journey. Whether you prefer a hands-on approach with spreadsheets or the convenience of automated apps, there’s a solution tailored for your style. The goal is to find a method that you will consistently use, as consistency is key to budgeting success.
Top Budgeting Tools and Methodologies
From simple pen and paper to sophisticated financial software, these resources can help you manage your money efficiently and visualize your progress.
- Budgeting Apps (e.g., Mint, YNAB, Personal Capital): These apps link directly to your bank accounts and credit cards, automatically categorizing transactions and providing real-time insights into your spending. Many offer features specifically designed to help you stick to budget rules like 50/30/20, with alerts and progress reports.
- Spreadsheets (Google Sheets, Excel): For those who prefer a more manual and customizable approach, spreadsheets offer complete control. You can create your own templates to track income and expenses, allowing for detailed categorization and analysis. Many free templates are available online.
- Envelope System: A physical budgeting method where you allocate cash into envelopes labeled for different spending categories (e.g., ‘Groceries,’ ‘Entertainment’). Once an envelope is empty, you stop spending in that category until the next budgeting period. This is particularly effective for managing ‘wants.’
- Financial Advisors: For complex financial situations or those seeking personalized guidance, a certified financial planner can help you create a tailored budget, invest wisely, and plan for long-term goals.
- Bank and Credit Union Tools: Many financial institutions now offer their own budgeting tools within their online banking platforms. These can be a convenient way to track spending directly where your money is held.
Regardless of the tools you choose, the most important aspect is regular engagement. Set aside time each week or month to review your budget, adjust categories as needed, and celebrate your progress. Consistent monitoring and proactive adjustments are what ultimately lead to mastering the 50/30/20 budget rule and achieving lasting financial freedom.
| Key Principle | Brief Description |
|---|---|
| 50% Needs | Allocate half of after-tax income to essential expenses like housing, food, and utilities. |
| 30% Wants | Dedicate 30% to discretionary spending, including entertainment, dining out, and hobbies. |
| 20% Savings & Debt | Commit 20% to building savings, investing, and paying down high-interest debt. |
| Flexibility | Adapt percentages to personal circumstances and review regularly for optimal financial health. |
Frequently asked questions about the 50/30/20 budget rule
The main benefit is its simplicity and clear structure, making it easy for US households to categorize expenses and prioritize financial goals. It provides a balanced approach to spending, saving, and debt management without being overly complicated, fostering financial discipline effectively.
‘Needs’ are essential for survival and basic living, like housing, utilities, groceries, and transportation. ‘Wants’ are discretionary expenses that improve your quality of life but are not strictly necessary, such as entertainment, dining out, and vacations. The distinction helps in making informed spending choices.
If your needs exceed 50%, it indicates a need to re-evaluate core expenses. Consider reducing costs where possible, such as finding more affordable housing or transportation. Alternatively, you might temporarily adjust the rule, perhaps to a 60/20/20 split, while actively working to reduce essential expenses.
Yes, contributions to retirement accounts like 401(k)s and IRAs are a crucial part of the 20% dedicated to savings and debt repayment. If these are pre-tax deductions, factor your budget based on your net pay, then count additional contributions as part of your 20% to ensure comprehensive financial planning.
It’s advisable to review your budget regularly, ideally quarterly or semi-annually. This allows you to account for changes in income, expenses, or financial goals. Regular adjustments ensure your budget remains relevant and effective, supporting your journey towards financial freedom.
Conclusion
Mastering the 50/30/20 budget rule offers US households in 2026 a clear and adaptable path to financial stability and growth. By diligently allocating income to needs, wants, and savings/debt repayment, individuals and families can gain control over their finances, reduce stress, and build a secure future. The flexibility of this rule allows for personalization, ensuring it remains a powerful tool regardless of individual circumstances or economic shifts. Embracing this framework, coupled with consistent review and the use of modern budgeting tools, empowers you to achieve your financial aspirations and navigate the complexities of personal finance with confidence.
