Retirement Planning for 2026: Maximize Your 401(k) by Age 40
Anúncios
To build a robust retirement fund, strategically maximizing your 401(k) contributions by age 40 in 2026 is crucial, taking full advantage of employer matches and catch-up provisions to accelerate wealth accumulation.
Anúncios
Effective retirement planning for 2026: maximizing your 401(k) contributions by age 40 is not merely a goal; it’s a strategic imperative for anyone aiming for financial independence. The earlier you start, the more powerful compounding becomes, turning modest contributions into substantial wealth over decades. This guide will explore actionable steps and insights to help you optimize your 401(k) well before your 40th birthday.
Anúncios
Understanding the 401(k) Landscape in 2026
The 401(k) remains a cornerstone of retirement savings for many Americans. As we approach 2026, it’s vital to grasp the current contribution limits, rules, and potential changes that could impact your saving strategy. Staying informed ensures you’re making the most of this powerful retirement vehicle.
Understanding the nuances of your 401(k) plan, including vesting schedules and investment options, is the first step toward maximizing its potential. Many employers offer a match, which is essentially free money, making it a critical component of your savings strategy. Ignoring this match means leaving significant funds on the table.
Contribution limits and catch-up provisions
For 2026, the IRS typically adjusts 401(k) contribution limits for inflation. It’s crucial to know these figures to ensure you’re contributing the maximum allowable amount. For individuals under 50, the standard employee contribution limit applies, while those aged 50 and over benefit from additional catch-up contributions.
- Standard Employee Contribution Limit: Understand the baseline maximum you can contribute from your salary.
- Employer Match: Always contribute at least enough to get the full employer match, if available.
- Catch-Up Contributions (Age 50+): While our focus is on age 40, knowing these future provisions can inform long-term planning.
These limits are designed to help you build a substantial nest egg, but they require consistent effort and a clear understanding of the rules. Reviewing your plan annually and adjusting your contributions as your income grows is a smart financial move. Don’t let potential changes to tax laws or plan specifics catch you off guard; proactive monitoring is key.
In conclusion, a solid understanding of the 401(k) framework for 2026, including contribution limits and employer match policies, forms the bedrock of an effective retirement savings plan. Being aware of these details allows you to optimize your contributions and take full advantage of the benefits offered.
Strategies for Maximizing Your 401(k) Contributions Early
Maximizing your 401(k) contributions by age 40 requires a proactive approach and a clear strategy. The power of compound interest works best with time, so starting early and contributing consistently are paramount. Even small, incremental increases can lead to significant gains over decades.
One of the most effective strategies is to automate your contributions. Setting up automatic deductions from your paycheck ensures that you consistently contribute without having to actively think about it. This removes the temptation to spend the money elsewhere and builds a disciplined saving habit.
Automating and increasing contributions
Automating your contributions is a simple yet powerful way to ensure consistency. Many employers allow you to set a percentage of your salary to be automatically deferred into your 401(k). This ‘set it and forget it’ method is highly effective.
- Start with a manageable percentage: Begin with an amount you’re comfortable with and gradually increase it.
- Automate increases: If your plan allows, schedule automatic increases to your contribution rate annually or with pay raises.
- Leverage employer match: Always contribute at least enough to receive the full employer match, as this is essentially a 100% return on that portion of your investment.
Beyond automation, actively seeking opportunities to increase your contributions is crucial. This could mean allocating a portion of bonuses, tax refunds, or unexpected windfalls directly to your 401(k). Every extra dollar contributed early has more time to grow, thanks to the magic of compound interest. This disciplined approach builds a strong foundation for your future.
In essence, maximizing early 401(k) contributions hinges on automating your savings and consistently seeking ways to increase those contributions. These disciplined practices will significantly amplify your retirement nest egg by the time you reach age 40 and beyond.
Leveraging Employer Match and Catch-Up Opportunities
The employer match is arguably the most valuable aspect of a 401(k) plan. It’s free money that significantly boosts your retirement savings without any additional effort on your part, beyond making your own contributions. Ignoring this benefit is akin to turning down a pay raise.
Understanding your employer’s specific matching policy is critical. Some companies offer a dollar-for-dollar match up to a certain percentage of your salary, while others might offer a 50% match. Knowing these details helps you contribute the optimal amount to maximize this benefit.
Optimizing your contributions for employer match
To fully capitalize on your employer’s match, you must contribute at least the percentage required to receive the maximum match. For instance, if your employer matches 100% of your contributions up to 5% of your salary, you should aim to contribute at least 5%.
- Identify your employer’s match formula: Understand how much they match and up to what percentage of your salary.
- Prioritize meeting the match: This should be your absolute minimum contribution goal.
- Review vesting schedules: Understand when employer contributions become fully yours.
While the primary focus is on maximizing contributions by age 40, it’s also prudent to be aware of catch-up contributions for those aged 50 and over. Although not directly applicable before 40, this knowledge can influence your long-term financial projections and provide a fallback if you find yourself behind on savings later in life. It emphasizes the importance of continuous saving throughout your career. Each year you meet the employer match, you are essentially adding thousands of dollars to your retirement fund that you wouldn’t have otherwise.
In summary, fully leveraging your employer’s 401(k) match is a non-negotiable strategy for accelerating your retirement savings. It represents an immediate, guaranteed return on your investment that is hard to beat elsewhere.
The Power of Compounding: Why Early Contributions Matter
The concept of compound interest is often referred to as the eighth wonder of the world, and for good reason. It’s the process where your investments earn returns, and then those returns themselves start earning returns. The earlier you begin contributing to your 401(k), the more time your money has to compound, leading to exponential growth.
Imagine two individuals: one starts saving at 25, another at 35. Even if the one who started earlier contributes less overall, they are likely to end up with a significantly larger nest egg due to the extended period of compounding. This illustrates why maximizing contributions by age 40 is so critical.
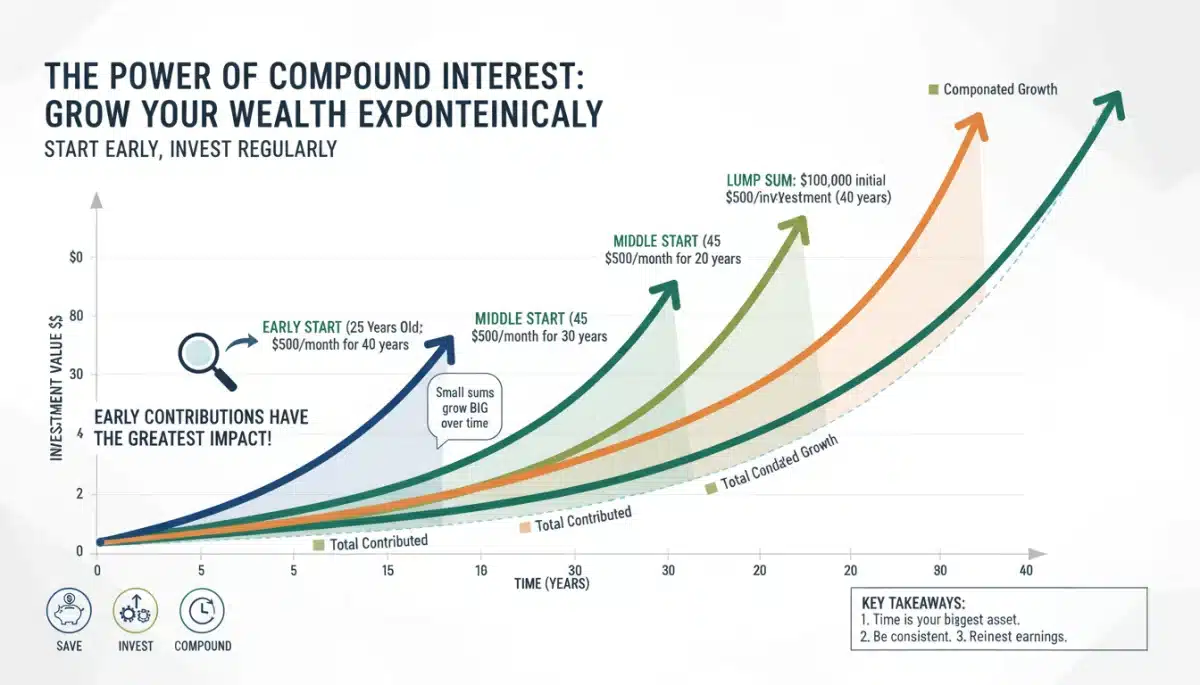
Illustrating long-term growth with compound interest
Consider a scenario where you contribute $500 per month starting at age 25 versus starting at age 35, assuming an average annual return of 7%. The difference in total accumulated wealth by retirement age (e.g., 65) is staggering. The extra ten years of compounding can result in hundreds of thousands of dollars more.
- Time is your greatest asset: Every year you delay saving means missing out on potential compounding growth.
- Even small contributions grow: Don’t underestimate the long-term impact of consistent, modest contributions.
- Reinvest earnings: Ensure your 401(k) plan automatically reinvests dividends and interest to maximize compounding.
This principle underscores the urgency of early retirement planning. By consistently contributing to your 401(k) and allowing your investments to grow untouched, you harness the full force of compounding. It’s not just about how much you save, but when you start saving that truly makes the difference. Many people regret not starting earlier; by age 40, you still have ample time to build a robust fund, provided you act decisively.
In essence, starting early to maximize your 401(k) contributions leverages the unparalleled power of compound interest, transforming even modest savings into substantial wealth over the long term. This makes proactive saving before age 40 an indispensable strategy.
Diversifying Your 401(k) Investments for Optimal Growth
While maximizing contributions is crucial, how you invest those contributions within your 401(k) is equally important. Diversification is key to managing risk and optimizing returns. A well-diversified portfolio helps protect your investments from market volatility and ensures steady growth over time.
Many 401(k) plans offer a range of investment options, from target-date funds to individual mutual funds and exchange-traded funds (ETFs). Understanding these options and selecting a mix that aligns with your risk tolerance and financial goals is essential for long-term success.
Selecting appropriate investment vehicles
Choosing the right investments within your 401(k) can feel daunting, but it’s a critical step. For those aiming to maximize growth by age 40, a more aggressive, growth-oriented portfolio might be suitable, given the long time horizon until retirement.
- Target-date funds: These funds automatically adjust their asset allocation as you approach retirement, offering a hands-off approach.
- Index funds and ETFs: Often provide broad market exposure with lower fees, making them excellent choices for diversification.
- Balance risk and return: Ensure your portfolio reflects your comfort level with risk while still aiming for substantial growth.
Regularly reviewing and rebalancing your portfolio ensures it remains aligned with your objectives. Market conditions change, and what was once an optimal allocation might not be so a few years down the line. By proactively managing your investments, you can mitigate risks and capitalize on growth opportunities. This ongoing vigilance is part of a holistic approach to maximizing your 401(k) before age 40.
Ultimately, diversifying your 401(k) investments wisely is paramount for achieving optimal growth and safeguarding your retirement savings. A balanced and regularly reviewed portfolio is key to navigating market fluctuations and securing your financial future.
Navigating Tax Advantages and Penalties
Understanding the tax implications of your 401(k) contributions is vital for maximizing your savings. Traditional 401(k)s offer immediate tax deductions, reducing your taxable income in the present. Roth 401(k)s, on the other hand, provide tax-free withdrawals in retirement, a significant advantage for those who anticipate being in a higher tax bracket later.
Beyond the immediate benefits, knowing the rules around early withdrawals and mandatory distributions can prevent costly penalties. Retirement accounts are designed for long-term savings, and the IRS imposes penalties for withdrawals made before age 59½, with some exceptions.
Traditional vs. Roth 401(k) and withdrawal rules
Choosing between a Traditional and Roth 401(k) depends largely on your current income and your projected income in retirement. Each option has distinct tax advantages that can significantly impact your overall financial picture.
- Traditional 401(k): Contributions are pre-tax, reducing current taxable income, but withdrawals are taxed in retirement.
- Roth 401(k): Contributions are after-tax, offering no immediate tax deduction, but qualified withdrawals in retirement are tax-free.
- Early Withdrawal Penalties: Understand the 10% penalty for withdrawals before age 59½, and common exceptions like disability or qualified first-time home purchases.
It’s also important to be aware of the Required Minimum Distributions (RMDs) that typically begin at a certain age (currently 73 for most). Failing to take RMDs can result in steep penalties. By being informed about these tax rules and potential penalties, you can make smarter decisions that protect and grow your retirement savings. This knowledge helps you strategically plan distributions and avoid unnecessary tax burdens, ultimately enhancing your retirement security.
In conclusion, a thorough understanding of the tax advantages and potential penalties associated with your 401(k) is essential. Making informed choices between Traditional and Roth options, and adhering to withdrawal rules, can significantly optimize your retirement savings.
Regular Review and Adjustment of Your Retirement Plan
A retirement plan is not a static document; it’s a dynamic strategy that requires regular review and adjustment. Life circumstances change, market conditions shift, and your financial goals may evolve. Periodically assessing your 401(k) and overall retirement strategy ensures you remain on track to meet your objectives.
Setting aside time annually to review your contributions, investment allocations, and overall progress is a best practice. This allows you to make necessary adjustments, such as increasing contributions, rebalancing your portfolio, or exploring other savings vehicles if needed.
Annual check-ups and adapting to life changes
An annual financial check-up is crucial for any robust retirement plan. This involves more than just looking at your 401(k) balance; it’s about evaluating your entire financial ecosystem and ensuring it supports your long-term goals.
- Review contribution rates: Are you still maximizing your contributions, especially after a pay raise or bonus?
- Assess investment performance: Is your portfolio performing as expected, and is its allocation still appropriate for your risk tolerance?
- Consider life events: Major life changes like marriage, children, or a new job warrant a review of your retirement plan.
Adapting to life changes is paramount. A new family member might mean adjusting your savings goals, while a career change could introduce new 401(k) options or require rolling over old accounts. Proactive management of your retirement plan ensures that it continues to serve your best interests, keeping you aligned with your goal of a secure retirement by age 40 and beyond. This ongoing engagement helps maintain momentum and address any potential shortfalls before they become significant issues.
In closing, consistent review and adjustment of your retirement plan are indispensable. By conducting annual check-ups and adapting to life’s inevitable changes, you ensure your 401(k) strategy remains robust and aligned with your evolving financial aspirations.
| Key Strategy | Brief Description |
|---|---|
| Maximize Employer Match | Contribute enough to your 401(k) to receive the full employer matching contribution, effectively getting free money for retirement. |
| Automate Contributions | Set up automatic payroll deductions to ensure consistent and regular contributions without manual effort. |
| Diversify Investments | Spread your investments across various asset classes within your 401(k) to manage risk and optimize long-term growth. |
| Understand Tax Rules | Be aware of Traditional vs. Roth 401(k) benefits and early withdrawal penalties to make informed tax-efficient decisions. |
Frequently Asked Questions About 401(k) Planning
The IRS typically adjusts 401(k) contribution limits annually for inflation. While specific 2026 figures are usually announced later, it’s essential to check the official IRS website or consult your plan administrator for the most up-to-date maximums for employee contributions.
Maximizing contributions by age 40 leverages the power of compound interest over a longer period. This allows your investments more time to grow exponentially, significantly increasing your total retirement savings compared to starting later, even with higher contributions.
The choice depends on your current and projected future tax bracket. A Traditional 401(k) offers immediate tax deductions. A Roth 401(k) provides tax-free withdrawals in retirement. If you expect to be in a higher tax bracket in retirement, Roth might be preferable.
Even if you can’t reach the maximum, aim to contribute at least enough to get your employer’s full match. Any amount you contribute consistently will benefit from compounding. Gradually increase your contributions as your income grows to get closer to the maximum.
It’s advisable to review your 401(k) investment allocations at least annually, or whenever a significant life event occurs (e.g., marriage, new job). This ensures your portfolio remains diversified, aligns with your risk tolerance, and supports your evolving retirement goals.
Conclusion
Successfully navigating retirement planning for 2026: maximizing your 401(k) contributions by age 40 is a cornerstone of financial security. By understanding current regulations, strategically leveraging employer matches, and harnessing the immense power of compound interest through early and consistent contributions, you lay a robust foundation for your future. Regular review of your investment allocations and an awareness of tax implications further refine your path. The journey to a comfortable retirement is a marathon, not a sprint, and proactive steps taken before age 40 can make all the difference in achieving your financial dreams. Embrace these strategies now to ensure a prosperous future.
