Urgent Alert: Major US Bank Announces 3-Month Grace Period for New Credit Card Regulations Starting January 2026
Anúncios
A major US bank has announced a three-month grace period for new credit card regulations starting January 2026, providing cardholders with essential time to understand and adjust to the upcoming changes before full enforcement.
Anúncios
An Urgent Alert: Major US Bank Announces 3-Month Grace Period for New Credit Card Regulations Starting January 2026 has sent ripples through the financial world, offering a critical window for millions of cardholders to prepare. This unexpected announcement provides a much-needed reprieve, allowing consumers and businesses alike to fully comprehend and adapt to the significant shifts coming to credit card usage and compliance.
Anúncios
Understanding the New Credit Card Regulations
The impending new credit card regulations, set to take effect in January 2026, represent a significant overhaul of existing financial guidelines. These changes aim to enhance consumer protection, improve transparency, and address emerging challenges in the credit card landscape. Understanding the core tenets of these regulations is the first step towards effective adaptation.
These regulations are not merely minor adjustments; they encompass broad areas of credit card operations, from interest rate calculations to dispute resolution processes. Consumers need to be aware of how these shifts will directly impact their everyday financial dealings and long-term credit health.
Key Areas of Regulatory Change
The new regulations touch upon several critical aspects of credit card management. These include stricter rules around late fees, clearer disclosure requirements for promotional rates, and enhanced protections against fraudulent activities. The goal is to create a more equitable and transparent environment for cardholders.
- Late Fee Caps: New limits on how much banks can charge for late payments.
- Interest Rate Transparency: Clearer explanations of how variable interest rates are calculated and applied.
- Dispute Resolution Improvements: Streamlined processes for consumers to challenge incorrect charges or fraudulent transactions.
- Account Closure Protocols: Stricter guidelines for banks when closing dormant or inactive accounts.
Ultimately, these regulatory changes are designed to foster greater trust between financial institutions and their customers. By setting clearer boundaries and expectations, the framework seeks to prevent predatory practices and ensure fair treatment for all credit card users. Staying informed about these specific changes is crucial for proactive financial planning.
The Significance of the 3-Month Grace Period
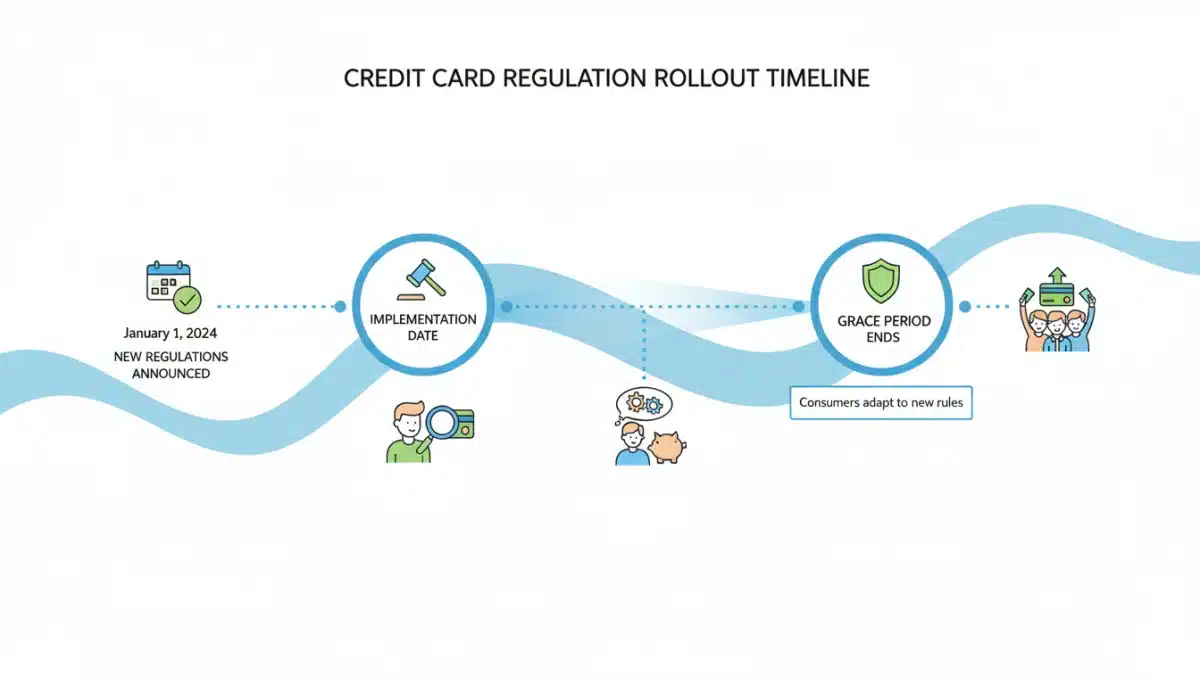
The announcement of a three-month grace period by a major US bank is a pivotal development, offering consumers and businesses a crucial window before the full enforcement of the new regulations. This period, extending from January to April 2026, is not merely a delay but an opportunity for preparation and adjustment. It underscores the complexity of the upcoming changes and the need for a gradual transition.
This grace period is a strategic move, acknowledging the potential disruption that immediate implementation could cause. It provides a buffer, allowing cardholders to familiarize themselves with the new rules without immediate punitive consequences for non-compliance. This proactive approach by the bank demonstrates a commitment to customer support during a period of significant financial adjustment.
What the Grace Period Entails
During these three months, while the new regulations officially commence, the bank will likely focus on educating customers and facilitating a smooth transition rather than imposing strict penalties. This means cardholders can expect enhanced communication, clearer statements, and accessible resources explaining the changes.
- Educational Resources: Banks will likely provide detailed guides and FAQs about the new rules.
- Customer Support: Increased availability of customer service representatives to address queries related to the regulations.
- Soft Enforcement: A period where minor non-compliance might result in warnings or guidance rather than immediate fines.
- System Adjustments: Time for both banks and consumers to ensure their systems and habits align with the new framework.
The grace period serves as a critical bridge, allowing individuals to align their financial practices with the new regulatory environment. It is an invaluable opportunity that should be utilized to review personal credit card usage, understand potential impacts, and make any necessary adjustments to avoid future complications.
Impact on Consumers and Cardholders
The new credit card regulations, even with a grace period, are poised to have a profound impact on consumers and cardholders across the United States. While the overarching goal is consumer protection, individual experiences will vary based on current credit practices and financial literacy. Understanding these potential impacts is essential for navigating the transition effectively.
For many, the changes could mean a more transparent and fairer credit card experience, particularly those who have previously struggled with hidden fees or complex terms. However, it also necessitates a proactive approach from cardholders to fully leverage the benefits and avoid any pitfalls that might arise from misunderstanding the new rules.
Navigating the Changes Effectively
Consumers should take this opportunity to review their existing credit card agreements and compare them against the upcoming regulations. This proactive step can help identify areas where personal financial habits might need to change. For example, understanding new limits on interest rate increases could inform decisions about carrying balances.
- Review Credit Card Statements: Pay close attention to any notices from your bank regarding the new regulations.
- Update Budgeting Strategies: Adjust your budget to account for potential changes in fees or interest calculations.
- Seek Financial Advice: Consult with financial advisors if you have complex credit card portfolios or concerns.
- Monitor Credit Reports: Regularly check your credit report for any discrepancies or unexpected changes resulting from the new rules.
The ultimate impact on consumers will largely depend on how well they adapt to these new guidelines. The grace period is a golden opportunity to get informed, ask questions, and make necessary adjustments to ensure a seamless transition into the new regulatory landscape.
Implications for Financial Institutions
While the new regulations directly affect consumers, financial institutions, particularly major US banks, bear the brunt of implementing and adhering to these complex changes. The announcement of a grace period by one such bank highlights the significant operational and strategic adjustments required. Banks must not only update their systems but also revise customer communication strategies and train staff.
Compliance with the new regulations is a multifaceted challenge, involving legal, technical, and customer service departments. The goal for banks is to ensure a smooth transition for their customers while maintaining operational efficiency and profitability. This period will test their agility and commitment to regulatory adherence.
Operational and Strategic Adjustments
Banks will need to invest heavily in technology upgrades to accommodate the new rules, especially concerning data reporting and transparency requirements. This includes reconfiguring billing systems, updating online banking platforms, and ensuring that all customer-facing interfaces reflect the new regulatory framework. The grace period provides essential time for these intricate system overhauls.
- System Overhaul: Updating core banking systems to comply with new fee structures and disclosure requirements.
- Staff Training: Educating employees on the revised regulations to ensure accurate information is provided to customers.
- Communication Strategy: Developing clear and concise communication plans to inform cardholders about the changes.
- Risk Assessment: Re-evaluating credit risk models in light of altered consumer behavior patterns under the new rules.
The implications extend beyond mere compliance; banks must also consider the competitive landscape. Those that successfully manage this transition, offering clear guidance and support to their customers, are likely to strengthen their customer relationships and market position. The grace period is an acknowledgment of the extensive internal work required to meet the January 2026 deadline.
Preparing for January 2026: A Proactive Approach
With the new credit card regulations looming and a grace period now confirmed, proactive preparation is paramount for both individual cardholders and businesses. January 2026 marks a significant shift, and waiting until the last minute could lead to confusion or financial setbacks. A structured approach to understanding and adapting to these changes is highly advisable.
This preparation should not be limited to merely reading the headlines. It involves delving into the specifics of how the new rules will affect personal finance or business operations. The grace period offers a valuable window to iron out any potential issues and ensure full compliance before the full force of the regulations takes effect.
Steps for Cardholders and Businesses
For cardholders, reviewing current credit card agreements and understanding how the new rules might alter interest rates, fees, or payment terms is a critical first step. Businesses, especially those that accept credit card payments, need to assess their processing systems and ensure they are compliant with any new transaction requirements or data security protocols.
- Stay Informed: Regularly check official announcements from your bank and regulatory bodies.
- Review Terms and Conditions: Carefully read any updated terms and conditions sent by your credit card issuer.
- Adjust Financial Habits: Modify spending or payment habits if new rules impact existing strategies.
- Seek Clarification: Do not hesitate to contact your bank or a financial expert for any uncertainties.
By taking these proactive steps, individuals and entities can transform what might otherwise be a challenging transition into a manageable and even beneficial adjustment. The grace period is an invitation to engage with the changes thoughtfully, ensuring financial well-being and regulatory compliance.
Long-Term Outlook of Credit Card Landscape
The introduction of new credit card regulations and the subsequent grace period are not isolated events but rather indicators of a continuously evolving financial landscape. Looking beyond January 2026, these changes are likely to shape the future of credit card usage, consumer behavior, and the strategies of financial institutions. The long-term outlook suggests a move towards greater transparency, consumer empowerment, and potentially more responsible lending practices.
This regulatory shift is part of a broader trend aimed at creating a more robust and fair financial system. It encourages both consumers and banks to engage with credit more thoughtfully, fostering a healthier overall credit environment. The repercussions will be felt for years to come, influencing product development, marketing, and customer service in the credit card industry.
Future Trends and Adaptations
In the long run, we can expect financial institutions to innovate in response to these regulations, potentially leading to new credit card products designed with transparency and consumer benefits at their core. Consumers, armed with more information and protections, may become more discerning in their credit choices, favoring issuers who prioritize clarity and fair terms.
- Enhanced Product Innovation: Banks may develop new credit card offerings that inherently comply with and highlight the new regulations.
- Increased Financial Literacy: Greater transparency might encourage consumers to deepen their understanding of credit products.
- Shift in Marketing Strategies: Banks may focus on ethical lending and transparent practices in their promotional campaigns.
- Strengthened Consumer Trust: Over time, the regulations could lead to higher trust levels between cardholders and financial institutions.
Ultimately, the long-term outlook suggests a credit card ecosystem that is more balanced and responsive to the needs of its users. The current regulatory changes, facilitated by the grace period, are foundational steps towards this more equitable and sustainable financial future.
| Key Point | Brief Description |
|---|---|
| New Regulations Start | New credit card rules officially begin in January 2026, focusing on consumer protection. |
| 3-Month Grace Period | A major US bank offers a grace period until April 2026 for adaptation, not full enforcement. |
| Consumer Impact | Cardholders need to review terms and adjust financial habits to new fee caps and transparency. |
| Bank Preparations | Financial institutions are updating systems, training staff, and refining communication strategies. |
Frequently Asked Questions About New Credit Card Regulations
The main goals are to enhance consumer protection, increase transparency in credit card terms, and ensure fair practices within the credit card industry. These regulations aim to make credit card usage clearer and safer for all cardholders.
While the specific bank is not named in this alert, a prominent US bank has announced a three-month grace period. This indicates a widespread industry awareness and preparation for the upcoming regulatory changes.
The grace period is for three months, starting in January 2026. It means that while the regulations are active, the bank will prioritize education and adaptation over strict penalties, giving you time to adjust.
You should review your current credit card agreements, stay informed through your bank’s communications, and consider adjusting your financial habits. Utilize the grace period to understand all changes thoroughly.
While one major bank has announced it, there’s no guarantee all banks will follow suit. It’s advisable to check directly with your specific credit card issuers about their plans for the new regulations.
Conclusion
The announcement of a three-month grace period by a major US bank for the new credit card regulations starting January 2026 is a critical development for millions. This window offers an invaluable opportunity for consumers and financial institutions alike to prepare for significant changes aimed at enhancing transparency and consumer protection. Proactive engagement with these updates, from understanding new fee structures to adjusting personal financial habits, will be key to a smooth transition. The long-term implications point towards a more accountable and user-friendly credit card landscape, fostering greater trust and financial stability for all stakeholders.
